Commercial Loan Renewal Automation: From Loan Register to Review
TL;DR
Commercial loan renewal automation connects maturity tracking, eligibility checks, account assessment and follow-up actions in one workflow.
Fluid AI’s demo shows a connected loan register, portfolio filters and AI-generated recommendations with supporting reasons.
Results are written back to designated fields on the original record, making progress visible to the team.
The agent prepares the assessment; the bank retains its renewal review and approval process.
A commercial loan is due for renewal in three days. The borrower’s limit is ₹3 crore, the outstanding balance is ₹2.46 crore, and the register shows no current overdue amount. The relationship manager still needs to check the renewal conditions, review the account, identify the documents required and record what happens next.
Now put that case inside a register containing thousands of loans. Some are approaching maturity. Some are already past due. Others have incomplete information, duplicate identifiers or assessments that have started but are difficult to track.
The challenge is keeping each case moving with the right information and a clear owner.
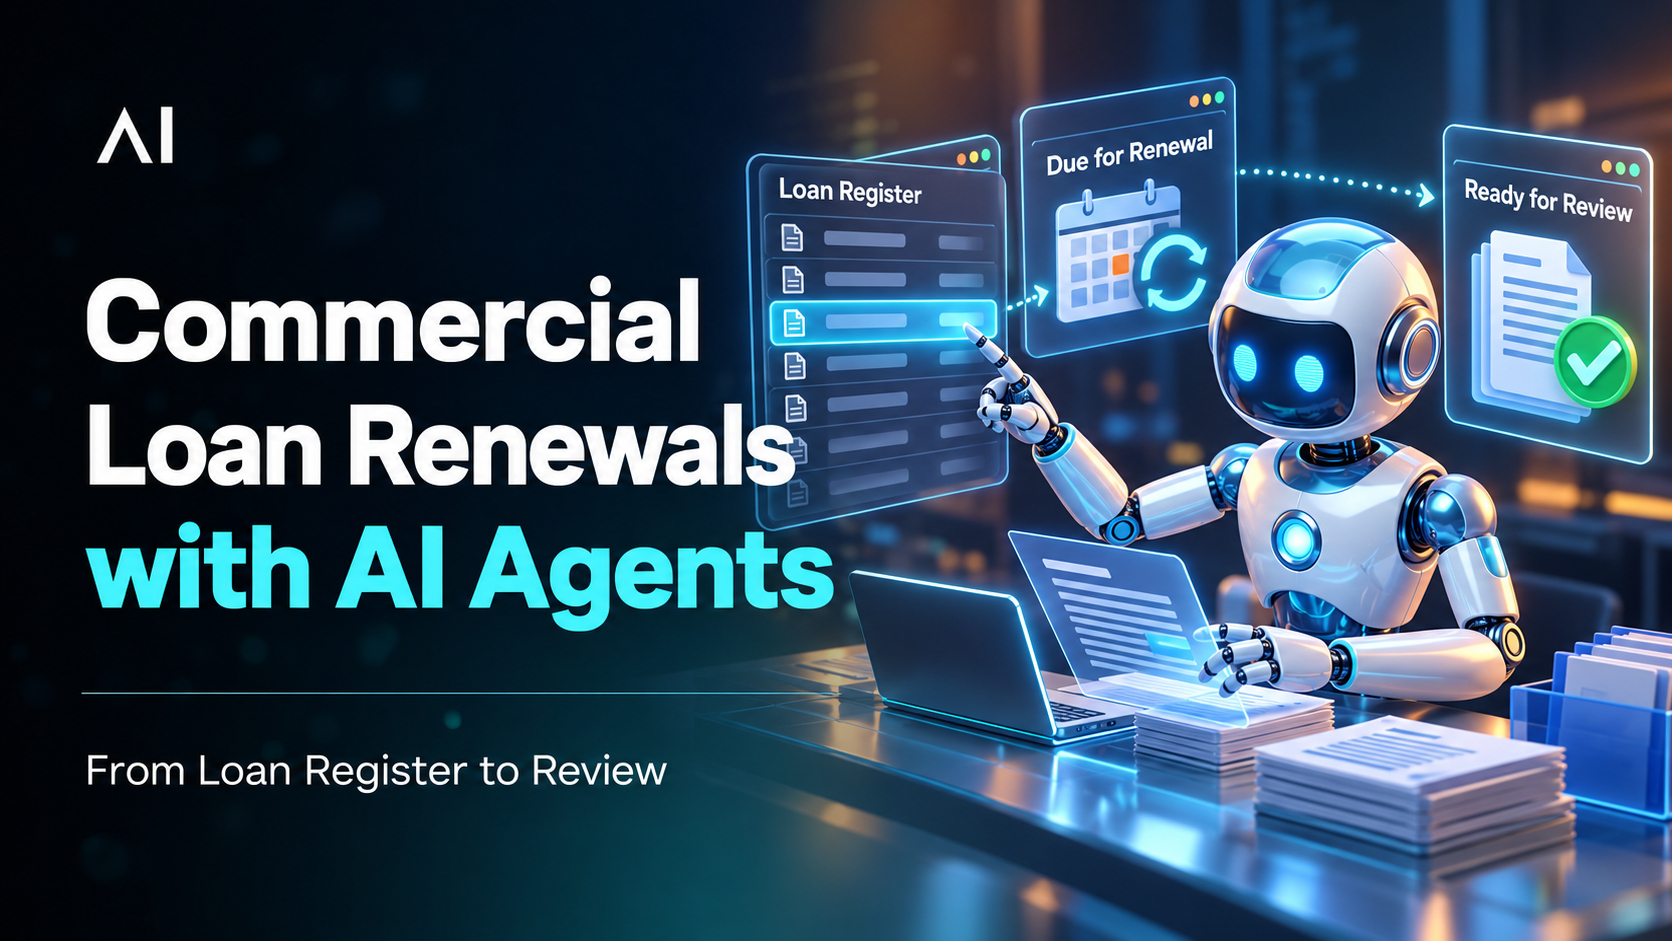
Commercial loan renewal automation connects the loan register to the work that follows: identifying cases, checking eligibility, preparing an assessment, assigning next actions and recording the output. Fluid AI’s Commercial Loan Renewal workflow demonstrates that sequence inside a single workspace, from portfolio view to individual loan record.
What is commercial loan renewal automation?
Commercial loan renewal automation is the use of software and AI agents to coordinate the review work around renewing an existing business loan. Depending on the workflow’s scope, this can include maturity tracking, eligibility checks, analysis of account information, preparation of renewal notes and updates to the systems used by the lending team.
The starting point differs from a new application. The bank already has a borrower relationship and an existing facility. The operational task is to bring the relevant account information into the renewal process and make the next steps clear.
Our guide to AI-powered loan origination explores the broader journey from application intake to credit review. Renewal automation addresses an adjacent need: managing review work across the existing loan book as facilities come due.
In the workflow shown here, the AI produces an assessment and recommended actions. An agent run marked “Completed” means that its task has finished. The facility’s renewal still follows the bank’s review and approval process.
Where manual loan renewal tracking becomes difficult
A spreadsheet can hold the information a team needs without making the next action obvious. The maturity date might be in one column, account utilization in another, and the latest progress update in an email.
That leaves the relationship manager or operations team to reconstruct the case before acting on it. Across a portfolio, several recurring problems emerge.
Finding the right cases to work on
A list sorted by date is useful, but teams also need to consider ownership, existing status and indicators that warrant attention. A loan approaching maturity with no assessment underway belongs in a different work queue from a case already being processed.
Turning account data into an actionable assessment
A credit limit, outstanding balance and overdue history are inputs. Someone must still interpret them against the workflow’s rules and explain the next step. Repeating that preparation manually takes attention away from cases that need deeper investigation.
Keeping the register aligned with the work
An assessment stored in a separate chat or document can leave the operating register out of date. Colleagues then have to ask whether a case has been reviewed, who owns it and where the output is stored.
A connected renewal workflow addresses these handoffs. It links the selected record to the assessment and gives the result a defined destination.
How Fluid AI’s loan renewal workflow works
1. Connect the register and confirm access
The demo begins with a request to open the renewal control tower for the commercial loan book. The user connects a Google Sheet, verifies the agent’s access and selects the tab and header row.
The connection supports reading the loan data and writing the assessment output back. The setup makes that permission requirement explicit, so the user can see why editing access is needed.
The demonstrated source is a Google Sheet. For a bank evaluating its own implementation, the corresponding design question is which approved register or application should supply the records and receive the results.
2. Map the columns to their business meaning
The platform identifies column roles for the borrower identifier, client name, due date, status, relationship manager and monetary values. The user can inspect those mappings before proceeding.
A preview also shows what one row will send to the agent. That matters when a register contains unfamiliar labels, empty dates or inconsistent values: the team can check how the workflow is interpreting the information before launching an assessment.
The setup separately identifies the output columns. This gives the workflow an explicit boundary between the information it reads and the fields it updates.
3. Narrow the portfolio to the cases that need attention
The demo displays 44,549 loan records in a maturity timeline and searchable table. The timeline shows past-due loans and upcoming maturities, with filters for relationship manager, segment, date, eligibility, overdue indicators and high utilization.
In the demonstrated sequence, selecting a particular maturity date narrows the view to 23 loans. A user can then launch the agent for an individual record or select eligible rows together.
The practical value is the transition from a large register to a focused queue. The displayed portfolio size illustrates navigation and selection in this demo; it is not a claim that all those loans were assessed during the video.
4. Verify the record and apply the eligibility check
The workflow’s initial gate checks the date and existing status. In the worked case, the facility is three days from maturity and the status field is blank, so the record qualifies for the demonstrated assessment.
The control tower also identifies duplicate customer IDs and disables the affected rows until the sheet is corrected. During the selected run, the activity view shows the agent re-reading the row and verifying its identifier.
These controls connect the assessment to the intended record. They also make a data problem visible before an output is written into the wrong place.
5. Assess the account and prepare the next actions
The agent reviews the available exposure, utilization and overdue history, then returns a recommendation with supporting reasons and actions for the relationship manager.
This gives the user a structured starting point: what the agent found, why it reached its recommendation and what the owner needs to do next.
Where a renewal requires deeper financial-document analysis, our article on AI-powered borrower risk assessment covers the related work of extracting financial information, calculating ratios and preparing a risk summary. That is a complementary capability; the renewal sequence shown here assesses the information available in its register.
6. Record the output against the original loan
At completion, the workflow writes the agent’s status, run identifier, output and update timestamp into four designated fields on the same row.
The user can open the assessment from the register and inspect what was produced. Colleagues working from that register can also see that an assessment exists, without relying on a separate message from the person who launched it.
Watch the commercial loan renewal workflow in action
The video below follows the workflow from connecting the register to filtering due loans, running assessments and writing the outputs back. Watch how the portfolio view leads into a single borrower’s recommendation and then returns to the updated record.
Commercial Loan Renewal Demo
Fluid AI’s Commercial Loan Renewal workflow: a connected register, visible agent activity and recorded next actions.
A worked example: from account figures to a renewal recommendation
One assessment in the video makes the workflow concrete. The selected loan has the following information:
Credit limit and outstanding balance
The borrower has a total credit limit of ₹3 crore, with ₹2.46 crore outstanding. This puts utilization at 82%.
Renewal timing
The facility matures in three days, and the existing renewal status is blank.
Current overdue position
The account shows no current overdue amount and zero overdue days.
Previous 12-month overdue history
The recorded maximum overdue amount over the previous 12 months is ₹0, with zero overdue days.
Under the demonstrated rules, the agent returns a “Renew” recommendation. It explains that the account is within the renewal window, utilization is below the example’s 85% threshold, and there is no current or recorded 12-month overdue amount.
The recommendation is accompanied by three specific next actions for the relationship manager:
Initiate renewal processing and update the case status to “In-progress.”
Collect the latest audited financial statements and stock statement before submission.
Confirm that the collateral valuation is less than 12 months old.
The thresholds and follow-up requirements belong to this demo scenario. A bank would define its own applicable rules and review requirements.
The useful output is the combination of assessment and handoff. The relationship manager can see the account context and the work still required. The listed document collection and valuation checks remain follow-up actions, rather than tasks shown as completed in the video.
How renewal automation fits with credit memo preparation
A renewal assessment may be one input into a more detailed credit submission. The register helps identify the case and establish its immediate account position; supporting documents and analysis provide the broader review material.
Our guide to AI credit memo automation explains how document extraction, financial spreading, policy checks and drafting can support that preparation. Connecting these stages is a useful implementation goal: an identified renewal case can lead into the bank’s document and memo process, with the appropriate review points.
The scope should remain clear. A short renewal note and a full credit memo serve different purposes. The workflow in this video produces the former, with next actions that help the relationship manager move the case forward.
Manual tracking and the demonstrated workflow, compared
Selecting cases for review
With manual tracking, teams sort the register and assemble a working list. In Fluid AI’s demo, users filter the portfolio by maturity date, relationship manager, eligibility and account indicators to identify the cases they want to assess.
Checking eligibility
A manual review requires someone to inspect the date and existing status of each selected loan. The demonstrated workflow applies its eligibility check and shows whether the record qualifies for assessment.
Preparing the assessment
The manual process involves reviewing account values and writing a note. The AI agent prepares a recommendation with supporting reasons and next actions for the relationship manager.
Tracking progress
Manual tracking relies on individual updates to establish what has been started or completed. The control tower displays queued, running and completed agent states, making assessment progress visible in the same workspace.
Recording the result
Without a connected workflow, someone must copy the assessment into the tracking record. In the demo, the agent writes its output, execution status, run identifier and update timestamp into designated fields on the original loan record.
This comparison describes the work shown in the demo. Actual time savings depend on the bank’s starting process, data quality, integrations and review requirements.
Visibility and control when agents update banking records
Once AI can update an operational record, teams need to understand what it read, what it produced and what it changed.
The demo makes several of those details visible: the row supplied to the agent, record-identity checks, activity during execution, the recommendation and the output fields. Agent completion is shown separately from the business status of the renewal.
That separation is important for users. “The assessment ran successfully” and “the bank approved the renewal” are different events, with different evidence behind them.
Our article on explainability in banking credit decisions explores why an output needs to be open to scrutiny. For a renewal workflow, that translates into practical review questions: which record supported the recommendation, what conditions were checked, and what still requires a person’s attention?
At portfolio scale, banks also need to plan how concurrent runs interact with shared systems. Our recent post on AI agents accessing enterprise systems at scale provides the wider infrastructure context. A renewal pilot should test retries, failed updates and simultaneous work on the same record before expanding its scope.
How to measure the value of a loan renewal automation pilot
Start with a defined portfolio segment and a clear outcome: an accurate, reviewable assessment written to the correct record, with an identifiable owner for the next step.
Then compare the existing process with the pilot across a representative set of cases. Include missing dates, duplicate identifiers, overdue accounts and cases already in progress, alongside straightforward renewals.
Preparation time: How much staff time is needed to produce an assessment ready for review?
Queue coverage: How many due cases have an assessment and an assigned next action?
Review quality: How often must a reviewer correct the facts, reasoning or recommended actions?
Update reliability: Are outputs recorded against the intended borrower and row?
Exception handling: Are incomplete or conflicting records clearly surfaced?
Cost per usable assessment: What does a completed, accepted result cost after retries and human review?
The last measure matters because a low model-call price says little about the total work required to finish a case. Our article on cost per task versus cost per token explains the broader measurement principle. For renewals, evaluate the cost of producing a usable result, including the effort needed to correct or rerun it.
For the wider lending business case, our article on automating credit memos in banking examines the value of reducing preparation work. A renewal pilot should similarly measure whether staff gain time for substantive review and whether cases move forward with less rework.
Book your Free Strategic Call to Advance Your Business with Generative AI!
Fluid AI is an AI company based in Mumbai. We help organisations kickstart their AI journey. If you're seeking a solution for your organisation to enhance customer support, boost employee productivity and make the most of your organisation's data, look no further.
Take the first step on this exciting journey by booking a Free Discovery Call with us today and let us help you make your organisation future-ready and unlock the full potential of AI for your organisation.
Frequently asked questions
Does the agent automatically approve a commercial loan renewal?
The demonstrated agent produces a recommendation and next actions, then records its output. A completed assessment is separate from the bank’s renewal approval and any changes to the facility.
What information does this renewal workflow use?
The demo uses a connected register with borrower identifiers, due dates, case status, relationship-manager ownership, limits, outstanding balances and overdue information. The required inputs for an implementation depend on the bank’s process and configured checks.
Can users assess several loans or schedule runs?
The interface supports selecting eligible rows and includes scheduling controls. The demo’s scheduling notice states that runs resend a captured row payload, so the team should confirm data-refresh behavior when designing recurring assessments.
Does the demo generate a complete credit memo?
It generates a renewal recommendation with reasons and follow-up actions. Full memo preparation is a related workflow with a broader document and analysis scope.